In the previous post, we explained the causes of the BoP Deficit in Nepal. Now, we will talk about how to adjust the BoP Disequilibrium.
BoP disequilibrium refers to the situation of either a deficit or a surplus, and the adjustment of such disequilibrium depends on the exchange rate system adopted by the country. If there is a flexible exchange rate system, then the BoP disequilibrium is adjusted through the market mechanism. If there is a fixed exchange rate system, then the disequilibrium is adjusted through the intervention of the central bank or monetary authority in the foreign exchange market.
1) Flexible exchange rate system & adjustment of BoP disequilibrium
BoP deficit = shortage of FOREX, then depreciation of domestic currency, then export↑, import↓ = (X-M)↑ = BoP deficit ↓ = BoP equilibrium
BoP Surplus = Appreciation of currency = export↓, import↑ = (X-M)↓ = BoP surplus ↑ = BoP equilibrium
In the case of a flexible exchange rate system, BoP disequilibrium is adjusted by the forex market itself. If there is a BoP deficit, it depreciates the value of the domestic currency, which encourages exports and discourages imports. So, net exports increase, which gradually reduces the BoP deficit and ultimately reaches equilibrium.
Similarly, if there is a BoP surplus, it appreciates the domestic currency. Then net exports decline and imports rise, which gradually reduces the BoP surplus and reaches equilibrium.
In order to explain the adjustment of BoP disequilibrium under the flexible exchange rate system, assume that the country has a BoP deficit.
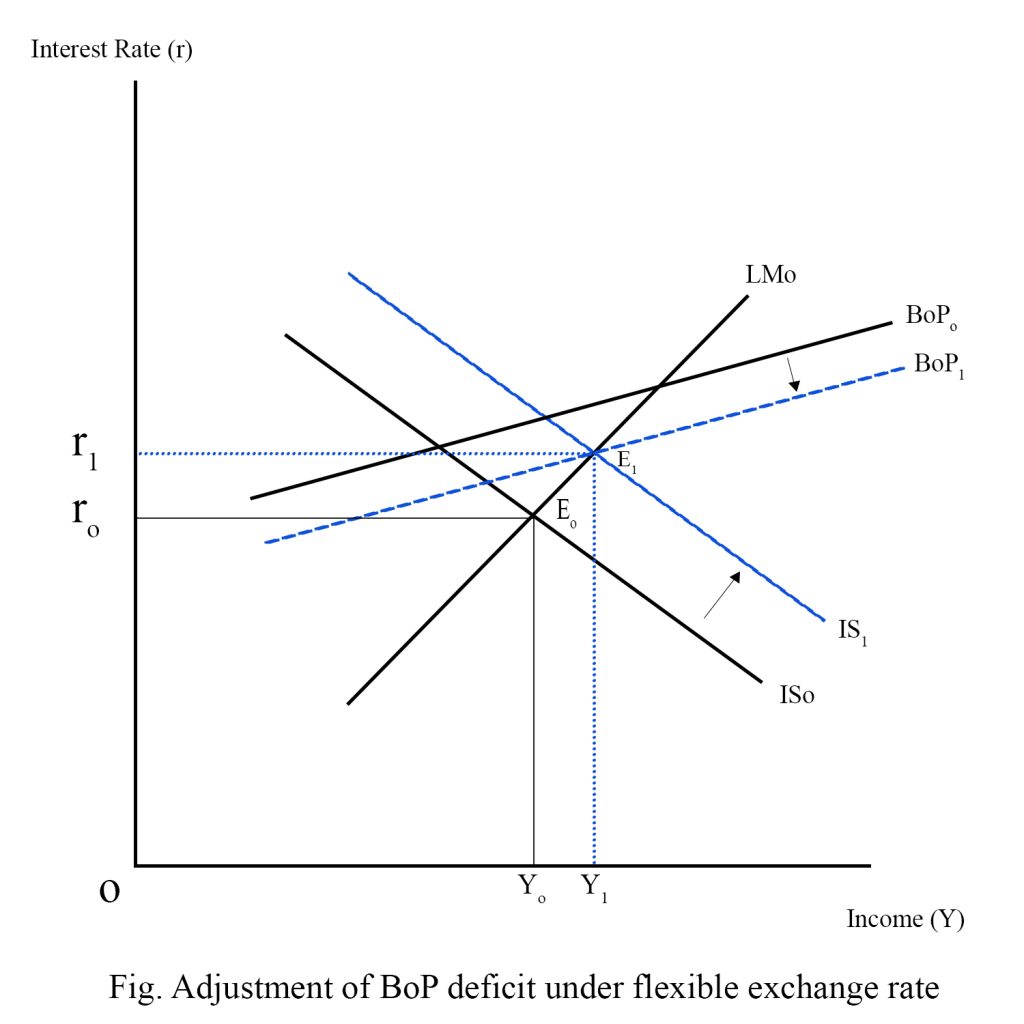
Here, the domestic (Internal) sector is initially in equilibrium at E0 with Ro interest rate and OY0 output (income).
Since this domestic equilibrium point E0 is below the BoP curve (BoPo), it represents a BoP deficit. Such a BoP deficit depreciates the value of domestic currency, which increases net exports. The increase in net exports shifts the IS and BoP curves rightward until they become IS1 and BoP1, which intersect the LM curve at E1. So the economy attains both the interest rate and output Oy1. This shows that under a flexible exchange rate system, the BoP deficit adjusts through the market by changing the exchange rate, which increases both the interest rate and output.
2) Fixed exchange rate system & adjustment of BoP disequilibrium
BoP deficit = shortage of foreign currency (FC) = NRB supplies FC to meet the market demand = Supply of NRs. ↓
In the fixed exchange rate system, the central bank or monetary authority is actively engaged in maintaining the fixed exchange rate. So, if there is a BoP deficit, the central bank supplies forex to the market to meet demand and prevent depreciation of the domestic currency. Similarly, if there is a BoP surplus, the central bank absorbs (buys) the excess forex from the market to prevent the appreciation of the domestic currency and maintain the fixed exchange rate. So, in the fixed exchange rate system, the central bank’s involvement in the forex market helps to adjust the BoP disequilibrium to BoP equilibrium.
BoP deficit = depreciation of the domestic currency if the central bank does not intervene in the forex market. But to maintain a fixed rate, the central bank supplies forex to meet shortages & keep the exchange rate.

Here, the domestic sector is initially in equilibrium at E0 with ro interest and OYo output. Since this equilibrium Eo is below the BoP curve, it represents a BoP deficit.
This BoP deficit depreciates the value of the domestic currency. It is a fixed exchange rate system, and to prevent depreciation of the domestic currency, the central bank supplies forex to meet the needs of the market, which ultimately reduces the Nepali currency in the market in such a way that the LM curve shifts leftward from LMo to LM’ and the economy attains a new equilibrium at E’ with r’ interest rate and oy’ output, at which both the internal and external sectors are simultaneously in equilibrium.
If such a fall in domestic money supply is not substantial and does not affect the aggregate demand and price level significantly, then the economy remains stable at E’ equilibrium with r’ interest rate & oy’ output. However, if such a fall in domestic money supply is substantial, then it reduces the aggregate demand and price level. The fall in the price level increases net exports, which shifts the IS and BoP curves rightward; as well as the fall in the price level increases the real money supply (M/p), which shifts the LM curve rightward from LM’. Such shift of LM, IS, BoP curve continues until LM1, IS1 and BoP1 and intersect with each other at E1 with r1 interest rate and Oy1 output.